Why does pre-mandate signal beat auction volume?
Because the information advantage still exists. Once a sell-side mandate is signed, your fund is one of dozens receiving the book, and the process is engineered to compress your edge to zero. The economics of proprietary deal flow rest on a simple asymmetry: the signals that precede a mandate — a founder crossing retirement age with no succession bench, a quiet AUM decline, a partner departure, an unusual capital-structure filing — are public, but almost nobody assembles them per firm and watches the trend.
The objective is not predicting the exact month a founder decides to sell. It is being the firm that has already had two good conversations when that decision happens.
The pre-mandate signal stack
Regulatory filings are the richest vein for financial-services targets: ADV amendments reveal AUM shifts, fee changes, ownership restructuring and disclosure events. For operating companies, Form D raises, state amendments and lien activity play the same role.
People signals — retirement-age founders, key-person departures, thinning leadership pages, succession-planning search behavior — are the strongest single predictor class for founder-owned businesses. Combine with hiring freezes or long-tenured-employee attrition for confirmation.
Financial-stress and transition markers: covenant-related filings, sale-leaseback activity, divisional divestitures, and advisory relationships appearing in public records.
- ADV / regulatory filing deltas (quarterly)
- Founder age & tenure model with succession-bench flag
- Executive departures and board changes
- Capital-structure events (raises, liens, refis)
- Web & search behavior around exit topics
- Hiring pattern shifts (freeze, backfill-only, C-suite search)
How do weak signals become a propensity-to-sell score?
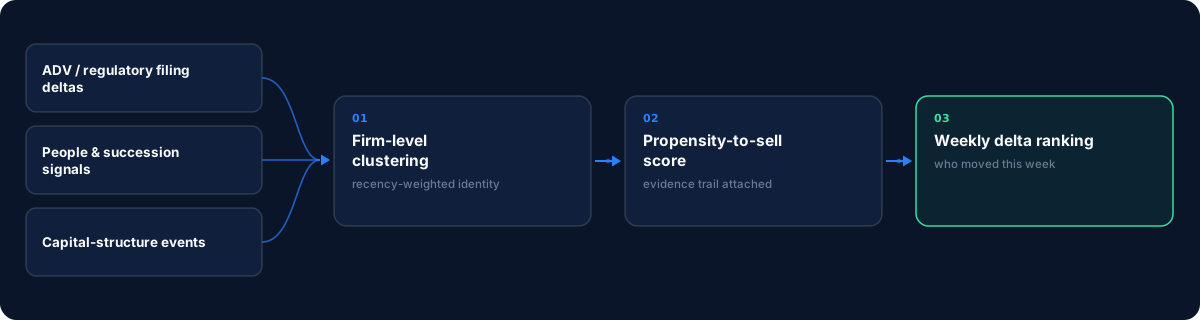
Through clustering, not thresholds. No single event justifies partner time. The operating model is: resolve every signal to a firm-level identity, weight by recency and severity, and rank the universe weekly by score delta rather than absolute score. 'Who moved this week' is a workable morning report; 'every firm above 70' is noise.
Score explainability is non-negotiable for investment committees. Every ranked target should carry its evidence trail — the filings, dates and changes behind the number — so an associate can verify in minutes and a partner can open the conversation with specifics rather than generic interest.
Outreach that matches the signal
Pre-mandate outreach fails when it sounds like coverage-list spam. The signal should shape the message: a succession flag suggests a conversation about continuity and legacy, not multiples; an AUM decline suggests a capability conversation. One well-timed, well-informed letter outperforms a quarter of cold emails.
Track conversations as pipeline with signal context attached, and re-rank on every new event. The fund that responds to a key-person departure within a week is having a different conversation than the one that finds out in the CIM.
How do you build a pre-mandate watchlist from scratch?
Start with the universe, not the signals. Define the target set the same way you would a coverage model: sector, size band, geography, ownership profile. For financial-services targets that usually means every SEC-registered adviser in a size band; for operating companies, a defined industry list. The watchlist is that universe plus a signal layer — not a list of leads someone sold you.
Then wire three feeds before touching anything exotic: quarterly regulatory filings (ADV amendments or state equivalents), people changes (departures, new hires, board shifts), and capital-structure events (Form D raises, liens, refinancings). Each feed must resolve to the same firm identity, or the clusters never form. Most teams can stand this up in a quarter with public sources; the hard part is the identity spine, which is exactly what a platform should supply.
Finally, set the cadence. A weekly delta review of 30 minutes beats a monthly deep-dive: the value of a pre-mandate signal decays with every week it sits unread. Assign each flagged firm to a named owner, log the outreach decision — engage, watch, or dismiss — and feed that disposition back into the ranking.
What results should a fund expect, and how fast?
Expect coverage before conversions. In the first 60 days the output is a ranked universe and a weekly who-moved report — the win is that associates stop manually scraping filings. Conversations typically start in the second quarter of operation, as clustered firms hit outreach thresholds; mandates and LOIs follow founder timelines, not yours.
The honest benchmark is share of proprietary conversations: what fraction of your live pipeline started from a signal rather than a banker email. Funds running signal-led sourcing typically aim for proprietary-first conversations on a meaningful share of their pipeline within two to three quarters — and the compounding asset is the relationship log, which keeps paying off as flagged firms mature toward a decision.
Glossary
- Propensity-to-sell score
- A clustered, recency-weighted score over succession, filing and capital-structure signals estimating transaction likelihood.
- Signal delta ranking
- Ranking targets by week-over-week score movement rather than absolute score, to surface newly-active situations.
Sources & further reading
- SEC — Investment Adviser Public Disclosure (IAPD) ↗
The primary source for ADV filings, AUM, ownership and disclosure events on registered advisers.
- SEC — EDGAR full-text search ↗
Form D capital raises and other filings, searchable the day they post.
- SEC — Form D (Notice of Exempt Offering) ↗
What a Form D actually discloses — and why it precedes capital-structure change.